Home / CSRD statement (ESRS)
CSRD · ESRS

A CSRD sustainability statement, structured by the ESRS

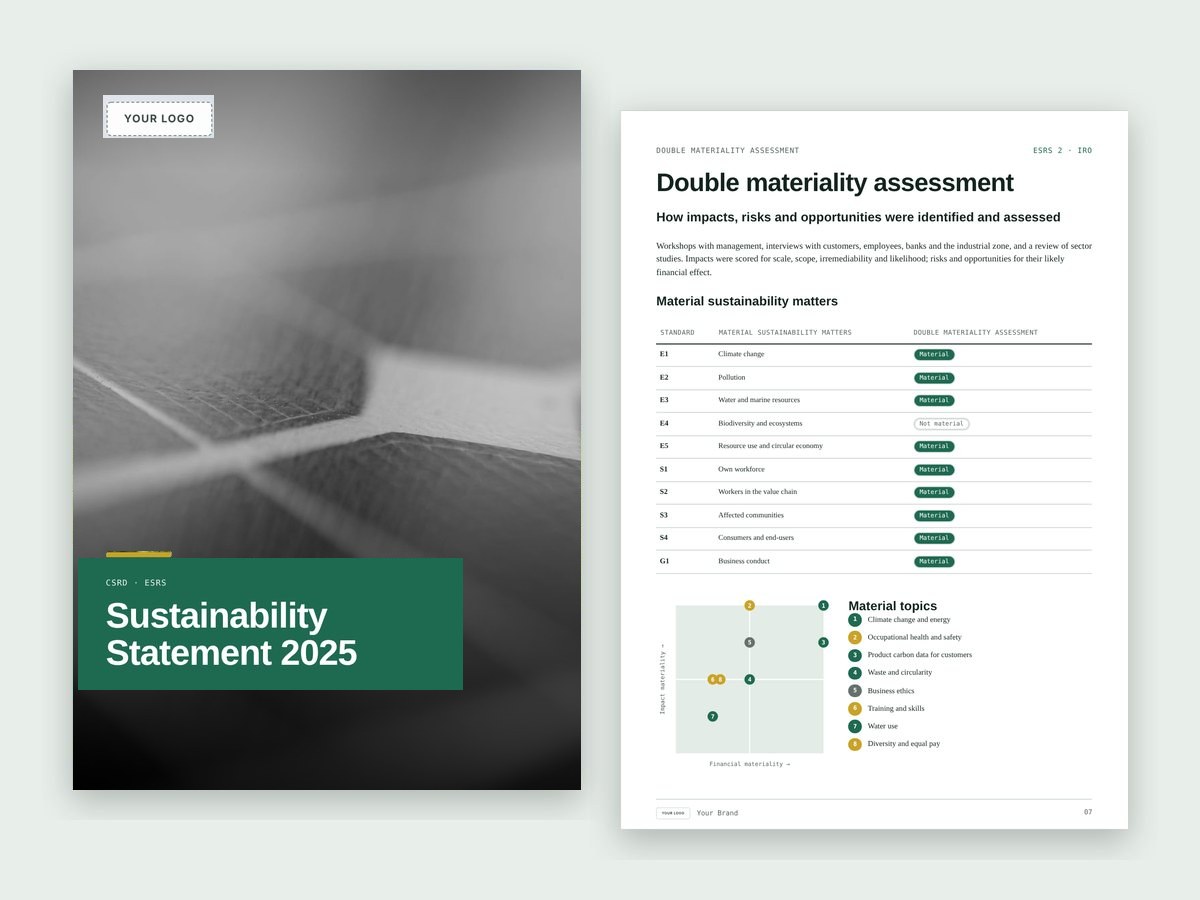
Basis for preparation, governance, strategy and value chain, a double materiality assessment with matrix, one chapter per material ESRS topic, payment practices, EU Taxonomy KPIs and an ESRS content index. Topics assessed as not material are left out and listed as such.

No report data is needed for the first call: we only discuss scope.

After the Omnibus simplification, the CSRD applies to companies with over 1,000 employees and over €450 million net turnover. Their statements follow the ESRS and need limited assurance.
CSRD statement (ESRS)

Who needs it

Companies in CSRD scope

A clear, designed sustainability statement that follows the ESRS structure.

Groups with EU subsidiaries

A consistent statement across entities, in eight languages.

Agencies and consultants

A fast first layout of the client's statement, ready for review and assurance.

What's in the report

  1. Basis for preparation (ESRS 2 BP)
  2. Governance, incentives and due diligence (GOV)
  3. Strategy, business model and stakeholders (SBM)
  4. Double materiality assessment and matrix (IRO)
  5. E1 Climate change: transition plan, energy, Scope 1–⁠3
  6. E2–E5: pollution, water, biodiversity, resources and waste
  7. S1–S4: own workforce, value chain workers, communities, consumers
  8. G1 Business conduct and payment practices
  9. EU Taxonomy KPIs and ESRS content index

Enterprise Delivery & Engagement Models

Enterprise turnkey deployment

CSRD statement (ESRS)

For holdings and listed groups: a multi⁠-⁠year microsite built from your published reports, with verified data, llms.txt and scope notes, delivered as a static package for your own domain.

Request an enterprise proposal and demo

Group companies, supply chain and audit partnership

Report family and white⁠-⁠label production

For multinational groups, subsidiary networks and Big Four / corporate advisory teams: a multi⁠-⁠report family (TSRS, CSRD/ESRS, GRI, Factbook, VSME) and white⁠-⁠label studio production.

Schedule an enterprise scoping call

The corporate quote and the official pro forma invoice are sent directly to your company e⁠-⁠mail address after the scope review.

The studio provides structure and design, not assurance, verification or legal advice.

Questions

Does it replace assurance or legal review?

No. The app gives the statement structure and design. Content, materiality assessment and assurance remain the company's and its auditor's responsibility.

Which ESRS version does it follow?

The topical structure of the ESRS (ESRS 2, E1–E5, S1–S4, G1), kept by the simplified 2026 standards. The content index works at disclosure⁠-⁠area level.

Can I reuse my ESG or VSME data?

Yes. Energy, emissions, water, waste, workforce and conduct figures, stakeholders, material topics and targets are shared across report types.

Other report types